The 10+1 scheme is an eleven-month relationship, not a payment plan
A monthly savings scheme gives a jeweller eleven months of contact with a committed customer. Most businesses treat it as a ledger entry. What that costs.
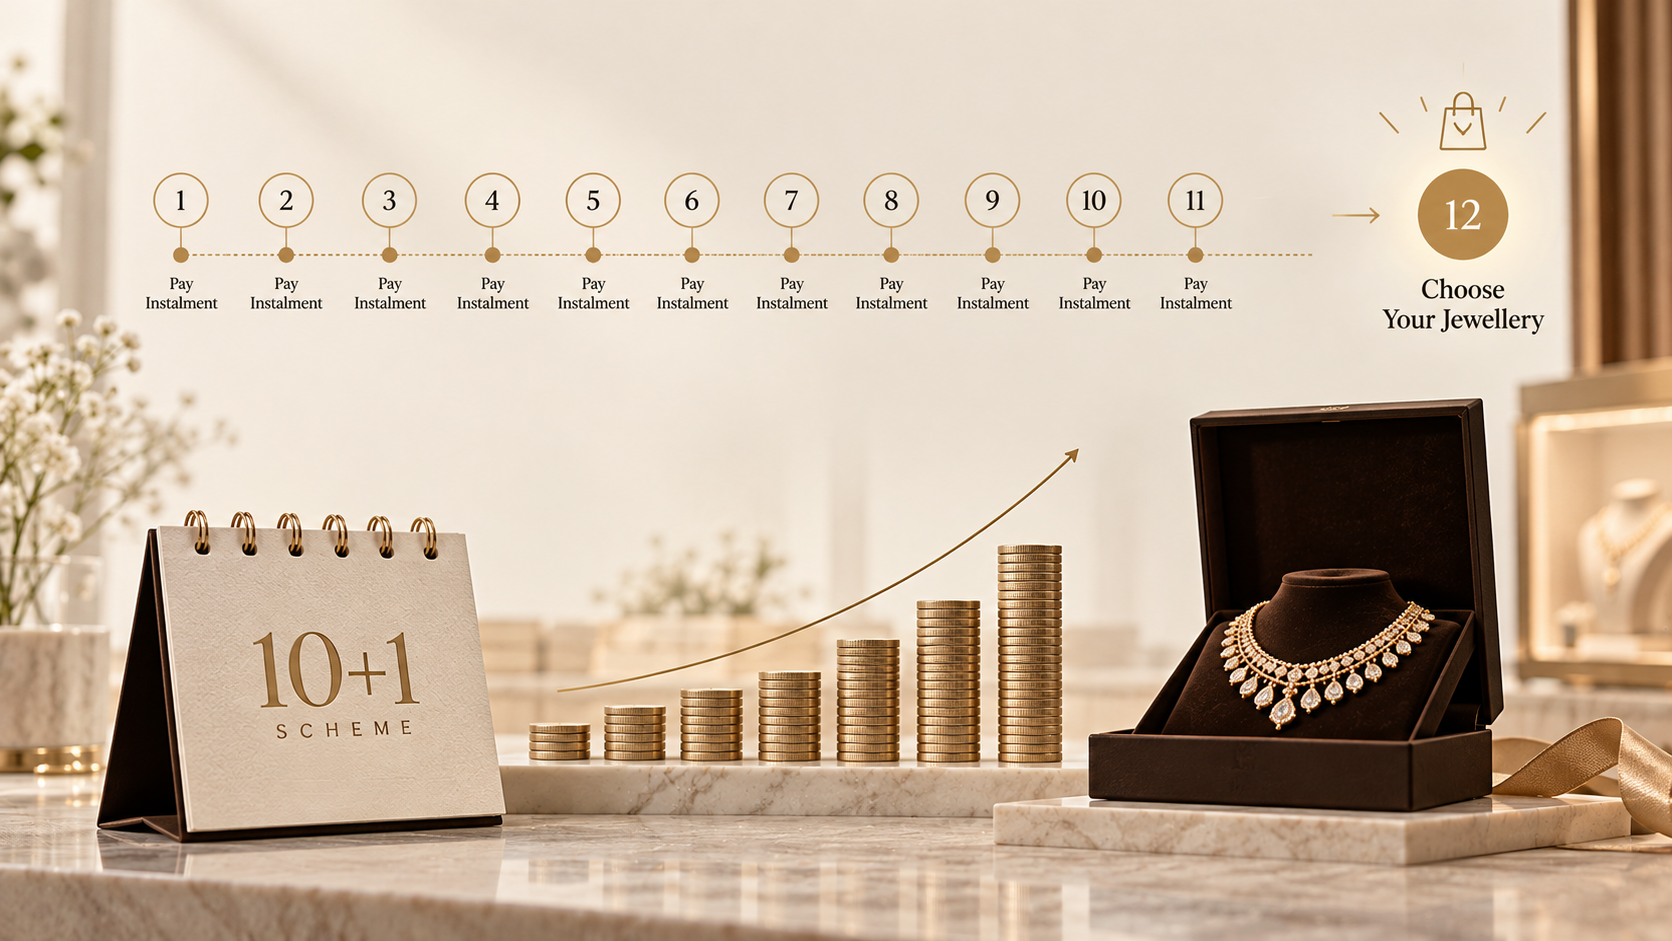
A customer joins a monthly jewellery savings scheme. For the next eleven months, she pays an instalment. In the twelfth month, she walks into the showroom to choose something she has been planning to buy.
For a jeweller, this is more than a recurring payment. It is eleven months of engagement with a customer who has already expressed an intention to purchase.
Yet many jewellery retailers treat those eleven months primarily as a collection process. An instalment comes in, a receipt is issued, and the ledger is updated. Reminders may be sent manually, while the customer's preferences, purchase intentions, and future requirements remain largely unexplored.
That is a missed opportunity.
A well-managed 10+1 jewellery savings scheme can become a structured customer relationship programme. It gives jewellers a predictable engagement cycle, an opportunity to understand customer preferences, and a chance to prepare for the eventual purchase before the customer arrives at the showroom.
The difference lies in how the scheme is managed: as a payment plan that needs administration, or as an eleven-month relationship that deserves attention.
What the 10+1 Scheme Actually Is, Commercially
A 10+1 scheme typically involves a customer making monthly contributions over eleven months, with a benefit applied according to the jeweller's scheme terms. The exact structure varies between retailers, so the benefit, redemption conditions, and eligible products must always be clearly defined.
From a commercial perspective, the most important feature is not the instalment itself. It is the recurring connection with a customer who has demonstrated an intention to buy jewellery.
Consider what a jeweller already knows when someone enrols:
- The customer has expressed an interest in purchasing jewellery.
- She has committed to a defined contribution schedule.
- Her expected maturity date is known.
- Her engagement with the brand can continue throughout the scheme period.
This information creates opportunities for thoughtful communication and better purchase planning.
For example, a customer saving towards a gold necklace may appreciate updates about relevant designs, new collections, or an upcoming family occasion. Another customer may be saving for a wedding purchase and require a different kind of assistance.
The scheme creates a natural reason to maintain contact. The challenge is making that contact useful rather than repetitive.
The commercial opportunity is to turn an existing payment relationship into a more informed, personalised shopping experience.
The Administration That Has to Be Right First
Before a jewellery savings scheme becomes a customer engagement tool, its administration must be accurate.
A retailer needs a clear record of every enrolled customer, the agreed instalment amount, payments received, outstanding amounts, scheme start date, maturity date, and applicable redemption terms.
The system must also account for exceptions. Customers may miss instalments, request clarification about their balance, seek an eligible transfer, or enquire about early closure. The applicable treatment depends on the scheme's documented terms and relevant legal requirements.
When this information is maintained across paper registers, spreadsheets, billing software, and individual store records, even a relatively small scheme can become difficult to manage.
A reliable scheme management process should support:
- Customer-level tracking: Every enrolment has a unique record and a complete payment history.
- Automated reminders: Customers receive timely instalment reminders through approved communication channels.
- Payment reconciliation: Recorded payments match the retailer's actual collection and accounting records.
- Maturity visibility: Staff can identify upcoming maturities and prepare for customer visits.
- Exception handling: Missed payments, disputes, corrections, and closures follow documented procedures.
- Auditability: Staff can trace changes to scheme records and explain the balance or redemption eligibility.
The objective is not simply to digitise a ledger. It is to establish a dependable operational foundation for every interaction that follows.
Compliance note: Jewellery savings schemes can have different legal and regulatory implications depending on their structure, payment arrangements, promotional claims, and applicable jurisdiction. Have the scheme terms, customer communications, accounting treatment, and relevant regulatory requirements reviewed by qualified legal and compliance professionals before launch.
Where Manual Scheme Management Breaks
Manual processes often work when enrolment numbers are low and one person knows every customer. They become harder to maintain as the business grows across multiple employees, showrooms, or franchise locations.
The first problem is fragmented information. A customer may make a payment at one branch, contact another branch for clarification, and eventually attempt redemption at a third. If each location maintains a different record, staff must reconcile the customer's history before they can provide a confident answer.
The second problem is inconsistent communication. One employee sends reminders promptly, another forgets, and a third maintains a separate spreadsheet. Customers receive an uneven experience even though they are participating in the same scheme.
The third problem appears at maturity. Without a central view of upcoming redemptions, staff may not know which customers are due to complete their schemes, what they are interested in purchasing, or whether suitable inventory is available.
These failures are not merely clerical inconveniences. They can affect customer trust.
A customer who has contributed for eleven months should not have to explain her payment history repeatedly or wait while staff search through multiple registers. The retailer should be able to provide an accurate account of her scheme and a clear explanation of her next steps.
Centralised scheme management helps replace fragmented records with a consistent customer experience.
Defaults and the Conversation Nobody Has
A missed instalment is often treated as an administrative exception. It can also be an opportunity to understand what the customer needs.
The appropriate response depends on the scheme's terms and the customer's circumstances. A system should not assume that every missed payment means the customer has lost interest.
At month three, a missed instalment might warrant a simple reminder and an easy way to confirm payment status. At month seven, repeated missed payments may justify a more personalised service conversation, provided the customer has appropriate communication preferences and the outreach remains respectful.
The difference is timing and context.
A useful scheme management system can identify:
- Which instalments are overdue.
- How frequently a customer has missed payments.
- Which customers may need clarification about scheme terms.
- Which accounts require staff follow-up.
- Which actions have already been taken.
Staff can then prioritise the right conversation rather than sending the same generic message to every customer.
The objective should be to help customers understand their options, not pressure them into paying. Any extension, reinstatement, adjustment, or other exception must follow the applicable scheme terms and authorised procedures.
Handled well, proactive communication reduces confusion and gives customers a clearer path through the scheme.
The Maturity Visit Is the Whole Point
The maturity date is not just a date on a payment schedule. It is the point at which months of contributions may turn into a jewellery purchase.
Yet many retailers prepare for this moment only when the customer arrives.
A better approach starts earlier.
If the retailer knows that a customer is approaching maturity, the store can prepare for a more useful conversation. Staff can confirm the customer's expected visit, explain the redemption process, review applicable benefits and conditions, and help her explore suitable designs.
Where the customer has voluntarily shared preferences or a purchase intention, the team can use that information to make relevant recommendations.
For example, a customer planning to purchase a necklace could receive an invitation to explore designs within her intended budget. A customer preparing for a wedding might appreciate an appointment with a jewellery consultant who can discuss matching pieces or complementary designs.
Inventory visibility also matters. If the desired design is unavailable at the customer's usual branch, the retailer may be able to identify an alternative or arrange an eligible inter-store transfer, subject to stock availability and business policy.
The important distinction is between a transactional maturity experience and a prepared shopping experience.
In the first, the customer arrives and the team starts gathering information.
In the second, the team already understands the scheme status, knows the redemption conditions, and is ready to help the customer make a decision.
What the Eleven Months Could Carry
A monthly scheme provides recurring opportunities for customer communication. But more communication does not automatically create more engagement.
The value comes from sending information that is relevant, timely, and consistent with the customer's preferences.
During the scheme period, a jeweller might share:
- Relevant new arrivals: Designs that match the customer's stated interests or intended purchase category.
- Occasion-based invitations: Invitations to explore collections ahead of a wedding, anniversary, or festival, where appropriate.
- Maturity preparation: Clear reminders about the expected maturity date, outstanding requirements, and redemption process.
- Personalised assistance: An opportunity to speak with a store representative or arrange a showroom appointment.
- Service updates: Accurate information about payments, account status, and applicable scheme terms.
A customer saving towards a particular purchase is different from someone casually browsing a jewellery catalogue. The retailer already has a reason to make the interaction more useful.
However, the scheme balance should not be treated as proof of the customer's exact spending capacity or purchasing preferences. Recommendations should reflect information the customer has actually provided, and promotional messages should respect consent, privacy requirements, and opt-out preferences.
The aim is not to turn every instalment reminder into an advertisement. It is to build a relationship in which the customer receives useful service throughout the scheme, not just at enrolment and redemption.
Schemes Across Multiple Stores
For a jewellery business with multiple showrooms or franchise locations, scheme management introduces another layer of complexity.
A customer may enrol at one branch, pay at another, and want to redeem at a third. Whether this is permitted depends on the scheme's terms and the retailer's operating model.
If cross-branch redemption is allowed, the system must make the customer's scheme status available to authorised staff across the relevant locations.
That means more than sharing a customer name and balance. The business needs a reliable way to establish:
- The customer's identity and scheme account.
- The instalments received and the current balance.
- The maturity date and applicable redemption conditions.
- The branch responsible for the transaction.
- The inventory allocated or sold at redemption.
- The financial settlement between locations, where applicable.
This becomes especially important in franchise environments. The branch that enrolled the customer may not be the branch that completes the sale. The business must define how the transaction is recorded, which location receives credit for the sale, and how any financial adjustments are handled.
A centralised system can provide a consistent view of the scheme while preserving appropriate store-level permissions and audit trails.
Without those controls, a promise of cross-store convenience can create reconciliation disputes behind the scenes.
Measuring Scheme Health
The number of active scheme accounts tells only part of the story. To understand whether a 10+1 programme is working, retailers need to measure both operational performance and the customer experience.
Four useful metrics are a practical starting point.
1. Enrolment and activation
Track the number of customers joining the scheme and the proportion who make their first scheduled payment. This helps distinguish initial interest from active participation.
2. Missed-instalment and default rates
Measure missed payments, recurring arrears, and accounts that reach the end of the scheme without completing the applicable requirements. Define each metric consistently so that different stores report comparable figures.
3. Maturity conversion rate
Measure the proportion of eligible matured schemes that result in a completed jewellery purchase within a clearly defined period. Exclude or separately report cases where the scheme terms, cancellations, or other circumstances make comparison inappropriate.
4. Average redemption value
Compare the value of completed redemptions with the amount accumulated under the scheme and any benefit applicable under its terms. This helps retailers understand purchasing patterns, but the calculation should distinguish customer contributions, scheme benefits, additional customer payments, and total sale value.
Retailers can also track reminder delivery, customer queries, maturity appointment attendance, and time taken to resolve payment discrepancies.
These metrics help identify where the programme needs attention. Low maturity conversion, for example, may reflect poor communication, an inconvenient redemption process, limited product availability, or simply a difference between customer plans and actual purchases.
The data should guide investigation rather than be treated as an automatic explanation.
Building a Better Scheme Experience with Jewellery Technology
As a jewellery retailer expands, managing savings schemes through disconnected registers and spreadsheets becomes increasingly difficult.
A connected jewellery technology platform can bring scheme records, customer information, payment history, reminders, store operations, and redemption workflows into a more consistent environment.
For retailers operating multiple showrooms, integration with the wider retail system can help authorised teams access the information they need without relying on manual updates between branches.
A platform such as JewelStack can support the broader digital operations of a jewellery business, including connected commerce and store workflows. The exact capabilities available for savings scheme management depend on the implementation and configured integrations.
The goal is not to automate every conversation. It is to give staff accurate information, reduce repetitive administration, and create more time for meaningful customer service.
When scheme administration is dependable, the business can focus on the relationship that the scheme was meant to create in the first place.
Frequently Asked Questions
How should jewellery savings schemes be tracked across stores?
Jewellery savings schemes should be tracked through a centralised system that records each customer's enrolment, instalments, outstanding balance, maturity date, and redemption status. Authorised branches should be able to access consistent records, while payment reconciliation and transaction audit trails help prevent discrepancies. Cross-store access and redemption should follow the scheme's documented terms and the retailer's operating policies.
What happens when a customer misses a scheme instalment?
The retailer should follow the missed-payment procedure documented in the scheme terms and communicate the customer's current status clearly. A system can flag overdue instalments, send appropriate reminders, and help staff identify accounts that need follow-up. Any grace period, benefit adjustment, reinstatement, or closure must be handled according to the applicable terms and legal requirements.
Can a customer redeem a jewellery scheme at a different branch?
A customer may be able to redeem a jewellery savings scheme at another branch if the scheme terms and retailer's policies permit it. The receiving branch needs access to the verified scheme balance, payment history, maturity status, and applicable redemption conditions. Multi-store businesses should also establish clear rules for inventory allocation, transaction ownership, and inter-branch settlement.
How do you increase conversion at scheme maturity?
Retailers can improve the maturity experience by identifying upcoming maturities early, communicating redemption requirements clearly, and offering relevant assistance based on the customer's stated preferences. Staff should be able to verify the scheme balance, check suitable inventory, and arrange an appointment where appropriate. Tracking maturity conversion alongside customer feedback helps identify process improvements without relying on pressure-based sales tactics.
Conclusion: Make Every Instalment Part of the Relationship
A 10+1 jewellery scheme creates more than a schedule of monthly collections. It establishes a period during which a jeweller can maintain contact, provide useful service, understand a customer's intentions, and prepare for a potential purchase.
That opportunity is wasted when the entire process revolves around receipts and reminders.
With accurate records, consistent communication, clear scheme terms, and a prepared maturity experience, jewellery retailers can make the eleven-month journey more valuable for both the business and the customer.
The payment plan is the mechanism. The relationship is the opportunity.